DealsFlow at ICAIF'26 in Milan: Lessons from the AI4F Workshop
Ming Ze Tang took DealsFlow to ACM ICAIF'26 in Milan to present Sapphire's research at the AI4F workshop. Here is what was shown, what was found and where the work goes next.
Several months of engineering, a poster in Milan and one simple rule: the AI reads and rates, and people decide.
Key takeaways: DealsFlow at ICAIF'26
We presented our poster, "DealsFlow: An Evidence-Gated Agentic Harness for Venture Capital Deal Triage", at the AI4F workshop, part of ACM ICAIF'26 in Milan.
Analyst time per application fell by 58%, from 44.7 to 18.9 minutes.
Across 142 mature SEIS and EIS deals, DealsFlow scored 0.71 at spotting which ones were later written off, against 0.68 for an AI left to its own devices. A score of 0.5 is a coin toss.
84% of the 240 claims DealsFlow cited were fully supported by their sources.
The design rule is simple: the AI reads and rates, code combines the scores and applies caps, and people make the decision.
What is DealsFlow?
DealsFlow is Sapphire's AI platform for screening venture deals. It reads an application, brings in external company data and runs a set of evidence checks, then produces a rating that gives analysts something structured to work from.
When Ming Ze started work on it, the goal was never simply to get AI to analyse startup pitch decks. The aim was to address a real challenge in venture capital: how do you make investment screening more efficient without compromising the quality of the assessment or losing the human judgement that matters?
That question shaped most of the build, from the multi-agent architecture and the use of external company data to the evidence checks, the deterministic scoring and the evaluation methods. The hardest part was making sure the system could justify its conclusions rather than simply produce convincing ones.
A poster, a crowd and two days of ideas on AI in finance.
What we presented in Milan
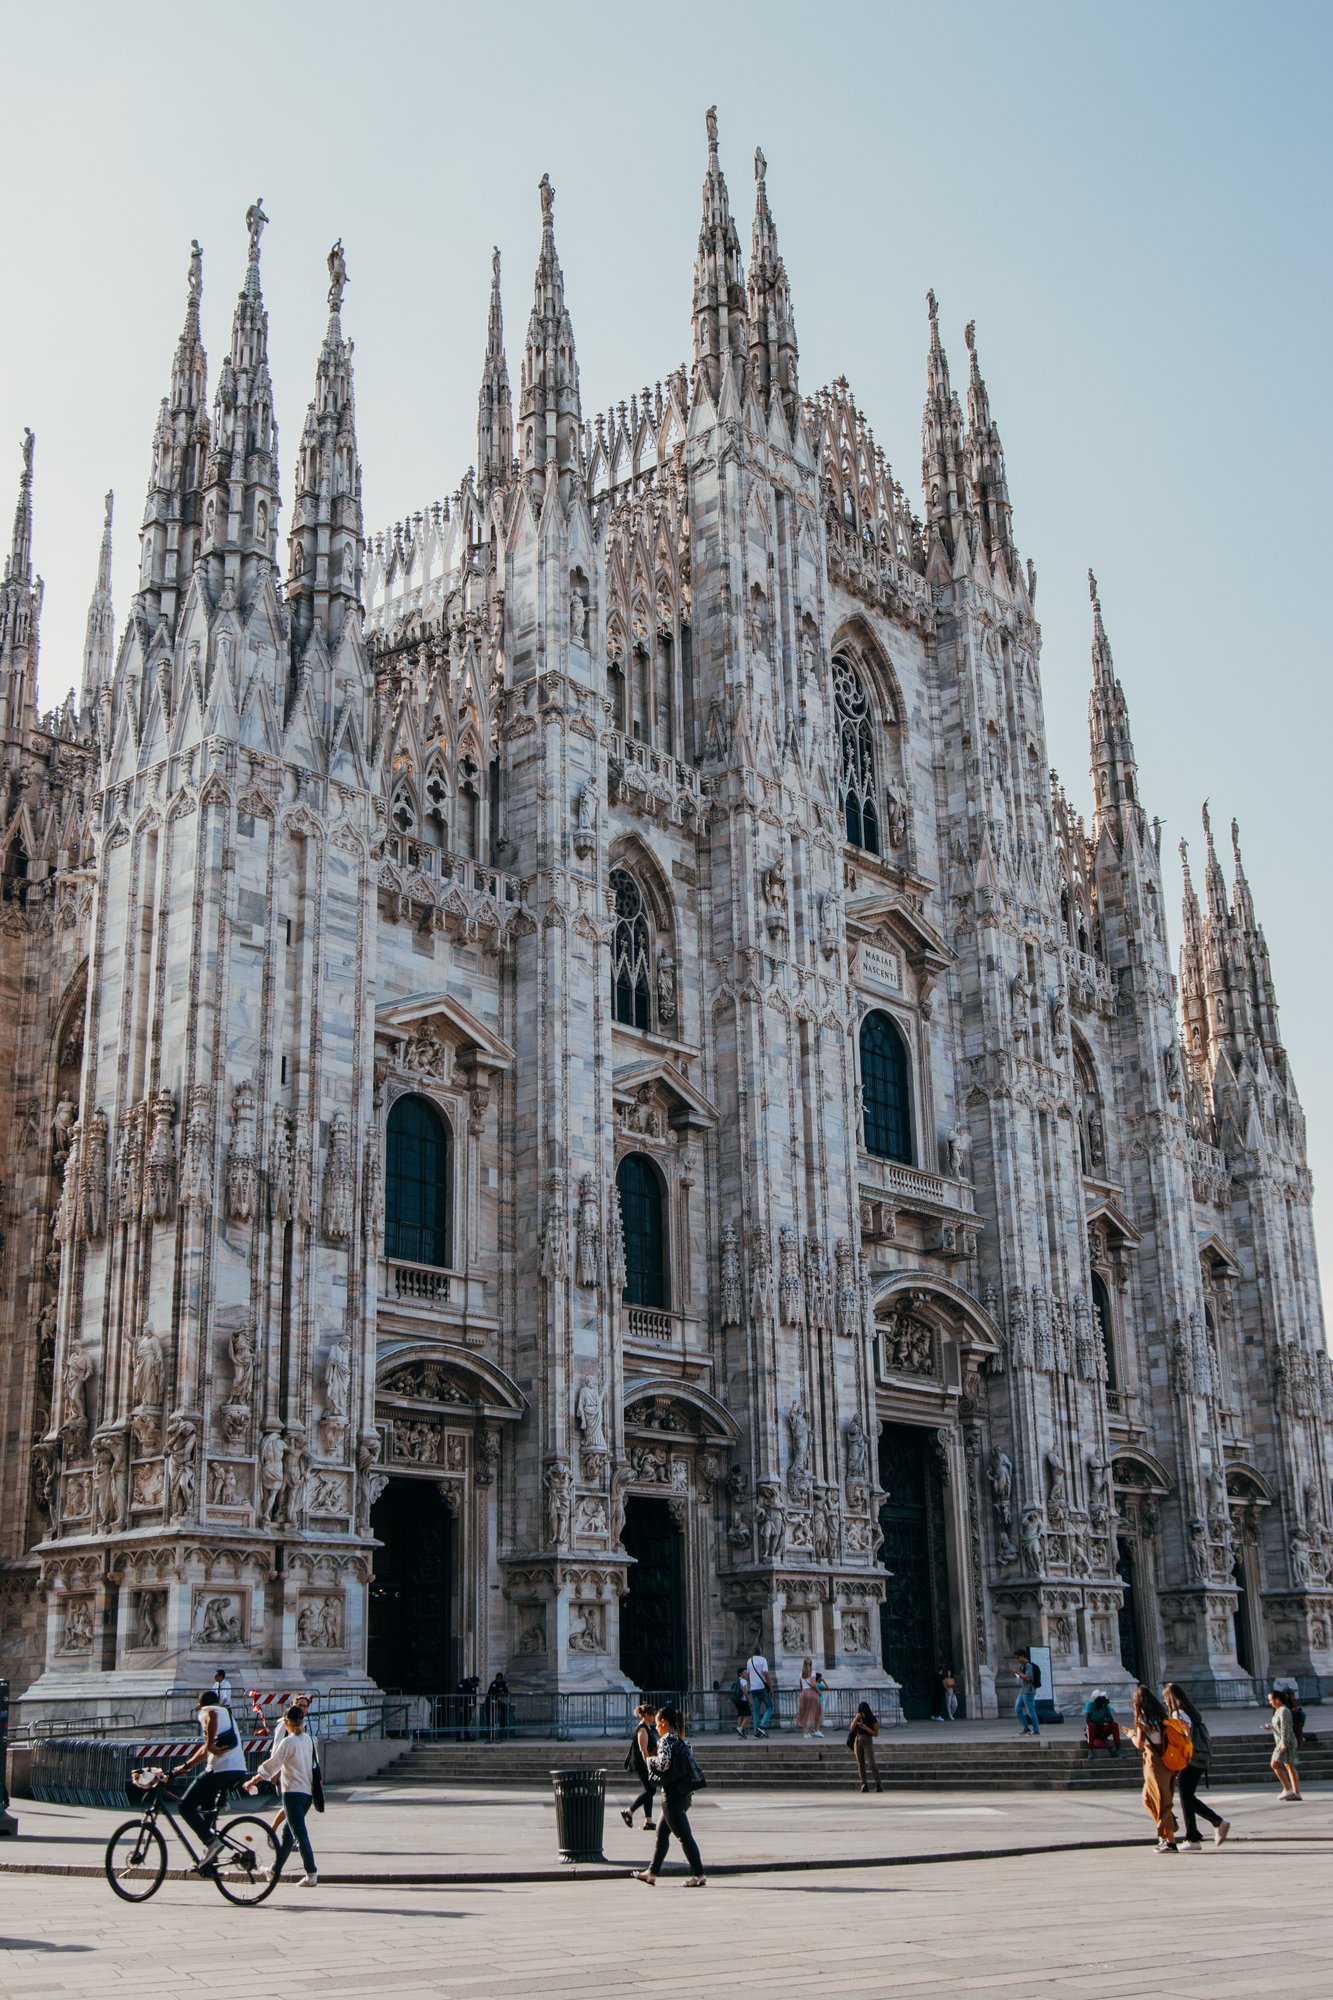
Our poster, DealsFlow: An Evidence-Gated Agentic Harness for Venture Capital Deal Triage, was presented at the AI4F workshop at ACM ICAIF '26 in Milan. The seventh ACM International Conference on AI in Finance ran from 14 to 17 November at Bocconi University, with the first two days given over to workshops and the main conference on the 16th and 17th. It was joint work with Dr David Cutting at Queen's University Belfast, supported by Innovate UK.
The idea is simple to state. The AI reads and rates each application, ordinary code combines the scores and applies caps that can only lower a rating, and people make the decision. The model never gets the last word.
In the room
The poster drew a crowd, which was the best part of the weekend. People gathered round to ask how the harness handles evidence, where it can be wrong and why the code is allowed to overrule the model. Those were exactly the right questions.
Sapphire's Chairman, Boyd Carson, joined for both days of the weekend workshops. It was good to compare notes with researchers and practitioners working on AI in finance, and Ming Ze came home with several ideas worth testing.
Evidence for every claim, less analyst time and a person still making the call.
What the results showed
We tested DealsFlow against the fund's own history. The portfolio holds 243 SEIS and EIS investments, but outcomes take years to show, and an investment that is still young cannot yet tell you whether it ends in a write-off. So we kept to the 142 mature deals, meaning investments at least three years old, where the outcome is much closer to settled. For context, SEIS is the Seed Enterprise Investment Scheme, which gives tax reliefs to individuals who buy new shares in small, early-stage companies, and EIS is its longer-established sibling.
The headline score was 0.71 for spotting which of those deals were later written off, against 0.68 for an AI left to its own devices, where 0.5 is a coin toss. That gap is modest and not one to oversell. It is also worth knowing that the stage-aware corroboration ceilings in the scoring rules were set well before this study and were not tuned on the evaluation data, so the result is not a set of rules fitted to the answer.
What matters just as much is whether the reasoning can be checked. Of the 240 claims DealsFlow cited, 84% were fully supported by their sources, which lets an analyst check the reasoning rather than take it on trust. A score nobody can audit is not much use in an investment committee.
On the practical side, analyst time per application fell by 58%, from 44.7 to 18.9 minutes. That is time that goes back into the judgement calls software should not make for you.
There is still plenty to build and improve.
Where we go from here
There is still a lot more to build and improve. The results are encouraging, but they come from one fund's portfolio, so the obvious next step is to test whether the pattern holds for other funds and other kinds of deal. The outcome labels are also time-censored: investments that are still young cannot yet show a write-off, so the numbers will keep shifting as the portfolio matures, and the evaluation will need rerunning as it does. One gap to close before leaning harder on any of this is run-to-run variation. Sapphire has not yet measured how much a score moves when the same application is processed twice.
The other thread is the human side. A 58% cut in analyst time only matters if the judgement that fills the gap is better, so the next question is how an evidence trail changes the conversation around a deal, from the first screen through to investment committee.
If anything, the trip has reinforced Ming Ze's interest in engineering AI systems that go beyond impressive demonstrations and deliver something measurable, reliable and useful in practice. It was a memorable weekend in Milan, and a milestone he is proud of.
Thank you to Dr David Cutting at Queen's University Belfast for his guidance and collaboration, to Boyd Carson, Vasiliki Carson and the whole team at Sapphire Capital Partners for trusting Ming Ze to develop this work, and to Innovate UK for supporting the project.
Common questions about DealsFlow
Who is DealsFlow for?
DealsFlow is for fund managers and analysts who screen early-stage deals, particularly SEIS, EIS and venture funds. It was built and tested on one fund's portfolio of 243 SEIS and EIS investments, so we have not yet shown that the same results hold for other kinds of fund or deal.
How is DealsFlow different from asking a general chatbot to screen a pitch deck?
A chatbot gives you one answer from one pass. DealsFlow separates the jobs: the AI reads and rates each application, ordinary code combines the scores and applies caps that can only lower a rating, and people make the decision. In our test across 142 mature deals, DealsFlow scored 0.71 at spotting later write-offs, against 0.68 for an AI left to its own devices. That gap is modest, and the bigger difference is that every claim is tied to a source.
Does DealsFlow replace analysts?
No. The model never has the last word. Analyst time per application fell by 58%, from 44.7 to 18.9 minutes, and that time goes back into the judgement calls software should not make.
Can DealsFlow's reasoning be checked?
Yes. Of the 240 claims DealsFlow cited, 84% were fully supported by their sources, so an analyst or investment committee can check the reasoning instead of taking a score on trust.
Who built DealsFlow?
DealsFlow was developed at Sapphire Capital Partners by Ming Ze Tang, in joint work with Dr David Cutting at Queen's University Belfast, and supported by Innovate UK.
How can I see DealsFlow in action?
You can book a demo and we will walk you through it using an example application.
See DealsFlow working on your own pipeline
If you run an EIS, SEIS or venture fund and want to see how an evidence-gated screen would sit alongside your analysts, book a short demo with Ming Ze.
